Contract Hire GAP Insurance

Nobody plans for their car to be written off, especially when they're still paying for it. Contract Hire GAP insurance helps cover the shortfall between your motor insurer's payout and what you still owe on your lease or contract hire agreement. One less thing to worry about if the worst happens.
Get a Free GAP Quote It only take a few minutes, prices start from £102.
Insure with trust
  • Financial Ombudsman Service
  • Financial Services Compensation Scheme
  • British Insurance Brokers Association

See your GAP in seconds

Depreciation’s sneaky. Here’s what it could cost you.

Say you paid £20,000 and have had the car for 3 years. If it’s lost 55% of its value, an insurer might pay about £9,000 after a write-off, leaving a gap of £11,000.

Figures are a rough guide, based on the car losing 55% of its value over 3 years. They’re not a valuation, or what any insurer will actually pay: that depends on your car, its condition and your policy. GAP cover terms, limits and exclusions apply.

Contract hire GAP insurance explained

  • The policy may pay the gap between your motor insurance settlement and the amount needed to settle your lease agreement.

  • This cover is specifically designed for eligible vehicles funded through a contract hire or lease agreement, not cash or loan purchases.

  • Cover may apply if your vehicle is stolen or seriously damaged and your comprehensive motor insurer treats it as a total loss.

  • The most the insurer will pay is the Maximum Benefit shown in your policy schedule, subject to the policy wording.

What our insurers can cover under contract hire GAP insurance

Contract hire GAP insurance can help if your leased vehicle is declared a total loss and your comprehensive motor insurance policy pays a settlement. Subject to the policy terms, the insurer may cover the shortfall between that settlement and the amount required to end the finance agreement. The policy does not cover every cost linked to a vehicle or finance agreement, and exclusions, eligibility rules and maximum benefit limits apply.

Total loss
Lease shortfall
Replacement

Lease agreement shortfall

May cover the difference between your motor insurer’s settlement and remaining eligible contract hire liability.

Total loss after theft

Can apply where theft results in a total loss payment from your comprehensive motor insurer.

Serious damage total loss

May respond when serious damage leads your motor insurer to declare the vehicle a total loss.

Eligible vehicle types

Designed for eligible passenger cars and light commercial vehicles shown on the policy schedule.

Private and business use

The policy can include Social, Domestic and Pleasure use, plus Business Class 1 and 2.

Replacement vehicle transfer

A policy may transfer if your motor insurer replaces the vehicle with the same specification after total loss.

Choosing the right contract hire GAP insurance

When reviewing contract hire GAP insurance, customers should consider their vehicle, finance agreement, motor insurance arrangements and the level of shortfall they may be responsible for after a total loss. It is important to check eligibility, exclusions, claim requirements, the Maximum Benefit and cancellation terms before buying. This information is not a personal recommendation, and customers should decide whether the policy meets their needs.

Finance

Your finance agreement

This policy is for vehicles on a lease or contract hire agreement. It does not cover vehicles bought with cash or a finance company loan.

Insurance Policy

Your motor insurance

You must keep a comprehensive motor insurance policy in place throughout the policy period. Motor trade insurance is excluded under the eligibility wording.

Eligibility

Vehicle eligibility

The vehicle must meet stated rules, including age, value, previous write-off status, source of purchase and permitted vehicle type requirements.

Costs

Costs that are not covered

Unrelated costs, arrears, missed payments, excess mileage, maintenance charges and certain finance fees are not covered by this policy.

Contract hire GAP insurance for leased vehicles

Contract hire GAP insurance is different from motor insurance. Your comprehensive motor insurance policy deals with insured damage or theft to the vehicle. GAP insurance may help with a separate issue: the difference between the motor insurer’s total loss settlement and the remaining eligible liability under your lease or contract hire agreement.

This policy does not cover the original invoice price or purchase cost. It is designed around the finance shortfall linked to an eligible lease agreement. Customers should read the IPID, policy wording and schedule together so they understand what is covered, what is excluded and the maximum amount payable.
A purple VW car sitting in a British street on a sunny day

Understanding contract hire GAP insurance limits and exclusions

Contract hire GAP insurance comes with limits and exclusions that potential customers need to understand before a policy is taken out. This cover is designed specially for vehicles leased through a contract hire or lease agreement, rather than a vehicle purchased outright or funded through a personal loan.

Typical exclusions include missed lease payments, arrears, charges for excess mileage, vehicle damage and other costs outside the agreed lease settlement amount. A claim resulting from a deliberate or criminal act may also be excluded, along with situations where you refuse a reasonable repair or replacement offer from your motor insurer. If you are VAT registered, this may also be excluded if you are able to reclaim it.

How does contract hire GAP insurance work?

  • Choose cover for an eligible lease or contract hire vehicle, checking the vehicle, agreement type and motor insurance requirements before buying.
  • Review the IPID, policy wording and schedule so you understand the Maximum Benefit, exclusions, eligibility rules and claim conditions.
  • Buy the policy through your insurance retailer and keep accurate information, complete documents and comprehensive motor insurance in place.
  • If the vehicle is declared a total loss, notify the claims handler promptly and provide required documents within 120 days.

GAP Insurance Expert

Nick Rinylo
Nick Rinylo
Insureworks Ltd

Contract hire GAP insurance can help with a specific finance shortfall after an eligible leased vehicle is declared a total loss. Customers should review the policy wording, IPID, schedule, exclusions, limits and eligibility requirements carefully before deciding whether the cover meets their needs.

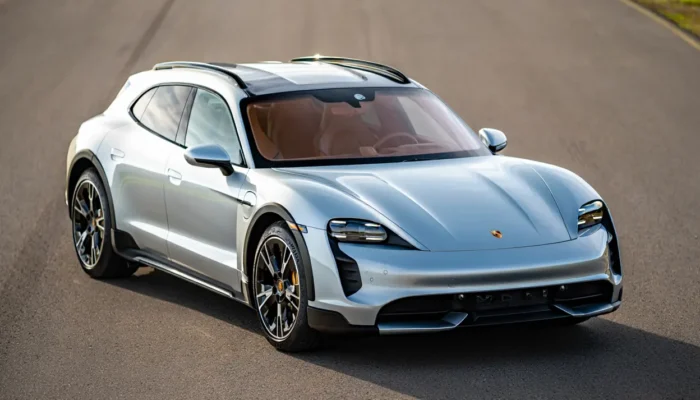
Silver Porsche Taycan Cross Turismo parked on an open road under daylight.
08 Sep 2025

My Porsche Taycan 4S GAP Insurance Claim

The Challenge In July 2023, I was involved in an accident that left my car a total write-off. The vehicle was just over 12 months old, and like most cars, it had already depreciated in value. The main insurer’s payout offer wouldn’t have even covered the outstanding finance. This would’ve left me with a nasty […]
Read more

GAP policy documents

Not exactly a page-turner, we know. But a quick skim before you buy could save you grief later.

Underwritten by Financial & Legal Insurance Company Limited

Cancellation

Cooling-off period

14 days

Changed your mind? Cancel within 14 days for a full refund. No reason needed, as long as you haven’t made a claim.

First 30 days

A full refund, as long as you haven’t claimed.

After 30 days

A refund for the days left on your policy, minus a £35 admin fee. Not available if you’ve claimed.

GAP insurance is underwritten by Financial & Legal Insurance Company Limited, which is authorised by the Prudential Regulation Authority and regulated by the Financial Conduct Authority and the Prudential Regulation Authority (Firm Reference Number 202915). It is administered by Nice 1 Limited, which is authorised and regulated by the Financial Conduct Authority (Firm Reference Number 650309). Claims are handled by AMS Insurance Services Ltd.

Latest GAP Insurance content

Contract Hire GAP Insurance FAQs

We know you might have questions; here are the five we hear at Insureworks the most.

Contract hire GAP insurance is designed for eligible vehicles on a lease or contract hire agreement. If the vehicle is declared a total loss and your comprehensive motor insurer pays a settlement, the policy may cover the shortfall between that settlement and the remaining eligible lease liability, up to the Maximum Benefit shown in your schedule.
Contract hire gap cover may include the difference between your motor insurance settlement and the amount required to settle your eligible lease or contract hire agreement after a total loss. Cover depends on the policy wording, schedule, eligibility rules, exclusions and maximum payment limit.
The policy does not cover vehicles bought with cash or a finance company loan. It also excludes costs not related to the finance agreement, missed payments, arrears, interest on arrears, deliberate or criminal acts, certain refused repair or replacement offers, and other listed exclusions.

In general terms, it may be relevant for customers with an eligible vehicle on a lease or contract hire agreement who want to understand how a finance shortfall could be handled after a total loss. This is not advice, and customers should check the documents before buying.

Start with the IPID, then read the Policy Schedule and policy wording together. Check which sections are selected, what limits and excesses apply, what is excluded and what obligations must be met. Customers should also make sure the information they provide is complete and accurate, and ask for clarification if anything is unclear.