Property Letting Insurance for the Office Itself

This covers the office your letting business runs from. It can include the office contents, computers and files, money on the premises and liability to a visitor. It is not landlord insurance. The properties you let, their buildings and contents, loss of rent and any liability at those properties all sit outside it.
Get Your Retail Business Insurance Quote It only takes a few minutes
Quick and easy checkout
No hidden fees
Online and phone support

Letting Agent Office Cover Explained

  • For letting agents, property managers and property owners in Great Britain, on an office only basis.

  • The properties you let are not covered here. No buildings, no contents, no loss of rent, no landlord liability.

  • There is no professional indemnity either. Claims about how a property was managed sit outside this product.

  • Only the sections shown as selected in your Policy Schedule apply, subject to terms and limits.

Business Insurance for Letting Agents: What Cover Can Include

The Lukango business insurance product can include property damage, public and products liability, business interruption following insured damage, money and assault and goods in transit. For a letting agent that means the office premises and what is in them, the desks and computers, the takings and the trade lost if the office cannot open. It does not extend to the properties on your books. Each section is subject to eligibility, terms, exclusions, excesses and limits.

Office
Contents
IT
Visitors
Money

Property damage

May cover insured damage to contents and equipment at the named office premises.

Public and products liability

Can help with certain third-party injury or damage claims arising at the office.

Business interruption

May cover trade lost following insured damage that stops the office opening.

Money and assault

Can include theft, attempted theft or robbery of business money, plus defined assault benefits.

Goods in transit

May cover eligible business property while in transit within Great Britain, including loading and unloading.

Property extensions

May include fixed glass and signage at the office, within the limits in the wording.

Choosing the Right Property Letting Insurance Cover

The first question with property letting insurance is whose property you are trying to insure. If the answer is the houses and flats on your books, this is not the product, and a landlord policy is what you are looking for. If the answer is the office you run the business from, this is built for exactly that: the contents, the computers, the money on the premises and the people who walk in. Read the IPID, Policy Schedule and full wording before deciding.

The let properties are not covered

The most important line on this page

Buildings, contents, fixtures, loss of rent and liability at the properties you let all sit outside this product. If that is what you came for, a landlord policy is the answer.

Nor is professional indemnity

Advice, valuations, management decisions

A claim that a property was managed, valued or advised on negligently is a professional indemnity matter. Nothing on this page should be read as cover for that, at any limit.

If you already hold landlord cover

For the portfolio, through another insurer

That is the situation this suits best. The portfolio sits on landlord policies and the agency office itself still needs insuring, which is the part most often overlooked.

The office is worth more than it looks

Computers, files, desks, front office

A letting agency office holds a surprising amount of kit and paperwork. Consider what replacing the computers, the furniture and the front office would actually cost today.

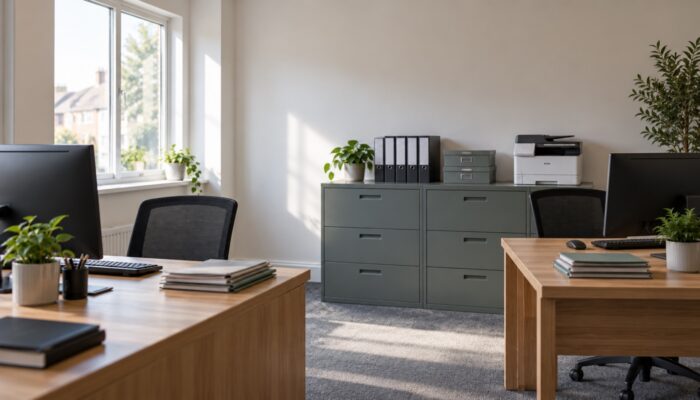
Two desks with computers, office chairs, filing cabinets and archive boxes in an empty letting agency

Letting Agency Insurance: The Office, Its Contents and Its Visitors

Property letting insurance under this product is cover for the business premises you work from and what is inside them. Property damage can include contents and equipment at the office named in your Schedule, where the section is selected and the loss is caused by an insured peril. That is the desks, the computers and the paperwork. Public liability can respond to injury or damage to a third party at the office, such as a visitor tripping in reception. It does not reach the properties you let, and no section of this policy does. The Policy Schedule confirms which sections apply, the sums insured, excesses and limits.
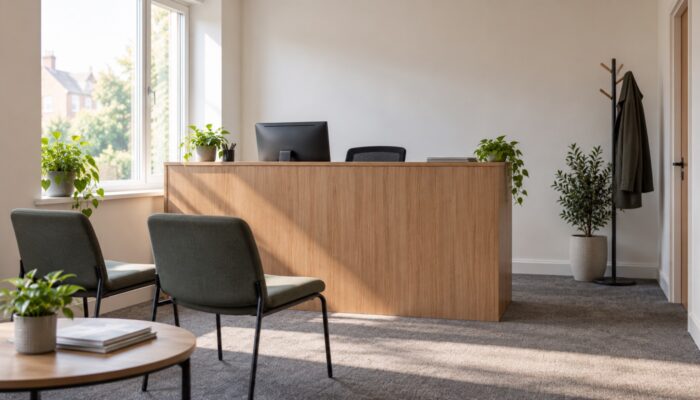
The reception counter and visitor chairs of an empty letting agency office beside a large window

Why Find Office Insurance Through Insureworks?

Insureworks is here to make finding insurance simple and transparent, and on this page that means drawing one line clearly. This is not landlord insurance and it is not professional indemnity. A landlord who buys it expecting cover for a let property has bought the wrong thing. What it does cover is the office a letting or managing agency runs from, which is a real exposure and an easy one to overlook. This page is information only and is not personal advice. Insureworks is not the insurer and does not underwrite or pay claims.

How Letting Agent Office Cover Works

  • Decide first whether you are insuring the properties you let or the office you work from, because this product only covers the second.
  • Review the IPID, Policy Schedule and policy wording to understand the selected cover, its limits, excesses, conditions and exclusions.
  • Provide complete and accurate information when arranging, renewing or changing the policy, including your activities and any material changes.
  • Notify a claim as soon as possible, provide requested evidence and report theft, malicious damage or criminal acts to the police.

Property Letting Insurance FAQs

Four questions we are asked most often about insuring a letting agency office.

No. This is an office only product. The buildings, contents and fixtures of the properties you let, loss of rent, and liability arising at those properties all sit outside it completely. Cover for a let property is a landlord policy and has to be arranged separately. What this covers is the office your letting or managing business operates from.

That is professional indemnity, and it is not part of this product. Claims about negligent management, valuation, inventory or advice need a professional indemnity policy arranged with an insurer that writes that risk. It is worth naming plainly because for a letting agent it is usually the largest professional exposure there is.

Where the relevant sections are selected: contents and equipment at the office named in your Schedule, business money on the premises, liability to third parties at the office, and trade lost following insured damage that stops you opening. Cover responds to insured perils rather than every cause of loss, and each section carries its own limits and excesses.

That is the situation this product suits best. If the properties are already on landlord cover, the agency office is the piece that often goes uninsured: the computers, the files, the furniture and the people who walk through the door. Check the two together so there is no gap between them.

Latest Retail Business Insurance Content