Pet Shop Insurance for the Shop Itself

This is cover for the shop and the business property in it: the premises, the fit-out, tanks and vivariums, the dry goods and accessories on the shelves, the takings and liability to customers on site. How live animals are treated is the first thing to confirm when you quote, because stock in this trade is alive.
Get Your Retail Business Insurance Quote It only takes a few minutes
Quick and easy checkout
No hidden fees
Online and phone support

Pet Shop Cover Explained

  • For pet shops and pet supply retailers in Great Britain, where the trade is on the accepted list.

  • Confirm at quote stage how live animals are treated. Do not assume they sit inside stock.

  • Tanks, vivariums, filtration and shelving are business contents at the premises in your Schedule.

  • Only the sections shown as selected in your Policy Schedule apply, subject to terms and limits.

Retail Insurance for Pet Shops: What Cover Can Include

The Lukango retail business insurance product can include property damage, public and products liability, business interruption following insured damage, money and assault and goods in transit. For a pet shop that means the premises and the fit-out, the tanks, vivariums and filtration, the food, bedding and accessories held as stock, the takings and the trade lost if the shop cannot open. Each section is subject to eligibility, terms, exclusions, excesses and limits.

Premises
Equipment
Dry goods
Customers
Money

Property damage

May cover insured damage to buildings, contents and stock at the named shop premises.

Public and products liability

Can help with certain third-party claims arising at the shop, and goods sold.

Business interruption

May cover trade lost following insured damage that stops the shop opening.

Money and assault

Can include theft, attempted theft or robbery of business money, plus defined assault benefits.

Goods in transit

May cover eligible stock while in transit within Great Britain, including loading and unloading.

Property extensions

May include fixed glass and signage at the shop, within the limits in the wording.

Choosing the Right Pet Shop Insurance Cover

The first question with pet shop insurance is one no other retail trade has to ask: what happens to the animals. Property damage covers contents and stock at the premises, and living stock is commonly treated differently from tins and bedding, so settle that before anything else. After that, the numbers that matter are the value of the fit-out, which in this trade means tanks, vivariums and filtration, and the dry goods held on the shelves.

Live animals

The first thing to settle, before anything else

Stock in a pet shop is alive, and living stock is commonly handled differently from ordinary stock. Confirm in writing how animals are treated before you rely on any cover here.

The fit-out is specialist

Tanks, vivariums, filtration, heating

A pet shop fit-out is closer to equipment than shelving, and a filtration or heating failure is a real exposure. Value it on what replacing the systems would cost today.

An animal and a customer

Worth raising at quote stage

Public liability can respond to certain third-party injury claims at the premises. How a claim involving an animal is treated is a question for the quote, not for a general web page.

Dry goods add up quietly

Food, bedding, accessories, tanks

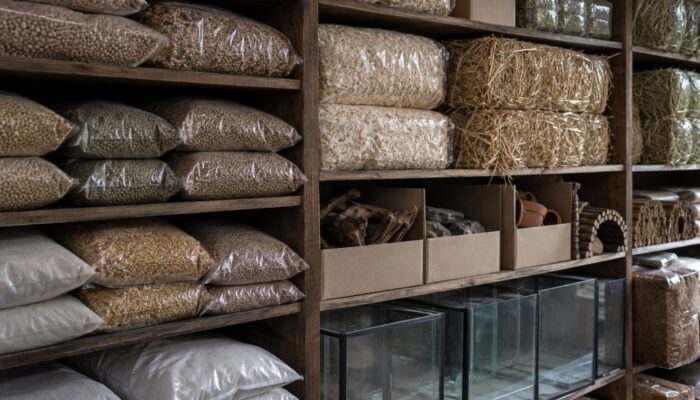
Sacks of feed, bedding, tanks and accessories are bulky and easy to under-count. Set the stock sum insured against what is genuinely on the shelves and in the stockroom.

Shelves of animal feed sacks, bedding, plain boxes and empty glass tanks in a pet shop stockroom

Pet Shop Insurance: Premises, Equipment and Dry Goods

Pet shop insurance under this product is cover for the shop and the business property in it. Property damage can include buildings, contents and stock at the premises named in your Schedule, where the section is selected and the loss is caused by an insured peril. That is the fit-out, the tanks, vivariums and filtration, and the food, bedding and accessories held for sale. Public liability can respond to injury or damage to a third party at the shop. How living animals are treated is a separate question to settle at quote stage. The Policy Schedule confirms which sections apply and their limits.
The timber sales counter of a pet shop with a till, scales, a roll of paper bags and a stool

Why Find Pet Shop Insurance Through Insureworks?

Insureworks is here to make finding insurance simple and transparent, and for a pet shop that means raising the awkward question first rather than last. Your stock breathes, and living stock is commonly treated differently from tins and bedding in a commercial property policy, so it needs confirming when you quote rather than assuming from a web page. What this product is built around is the shop itself: the premises, the specialist fit-out, the dry goods and the people who come in. This page is information only and is not personal advice. Insureworks is not the insurer and does not underwrite or pay claims.

How Pet Shop Cover Works

  • Confirm first how live animals are treated, because stock in this trade is alive and that is not a general question.
  • Review the IPID, Policy Schedule and policy wording to understand the selected cover, its limits, excesses, conditions and exclusions.
  • Provide complete and accurate information when arranging, renewing or changing the policy, including your activities and any material changes.
  • Notify a claim as soon as possible, provide requested evidence and report theft, malicious damage or criminal acts to the police.

Pet Shop Insurance FAQs

Four questions we are asked most often about insuring a pet shop.

That is the question to settle before anything else, and this page cannot answer it for your business. Property damage covers contents and stock at the premises, and living stock is commonly treated differently from ordinary stock in a commercial property policy. Get it confirmed in writing at quote stage rather than assuming it either way.

Equipment of that kind can be included as business contents at the premises named in your Schedule where the property damage section is selected. A pet shop fit-out is closer to machinery than shelving, so it is worth valuing on replacement cost and reading how the wording treats breakdown as distinct from insured damage.

Public liability can respond to certain third-party injury or damage claims arising at your premises, subject to the terms, exclusions and limits that apply to your policy. Whether a claim involving an animal is treated the same way is a question to raise at quote stage, because it is not something a general page should answer for you.

Dry goods held for sale can be included under the property damage section where that section is selected, subject to the sum insured and any limits. Feed and bedding are bulky and easy to under-count, so the figure should reflect what is genuinely held in the shop and the stockroom rather than a rough estimate.

Latest Retail Business Insurance Content