Furniture Shop Insurance for the Shop Itself

This is cover for the showroom and what is in it: the premises, the fit-out, the floor stock and the takings. It is also the trade here that really uses the goods in transit section, because your stock spends its last day in a van. How delivery into a customer's home is treated is the thing to confirm.
Get Your Retail Business Insurance Quote It only takes a few minutes
Quick and easy checkout
No hidden fees
Online and phone support

Furniture Shop Cover Explained

  • For furniture retailers in Great Britain, where the trade is on the accepted list.

  • Goods in transit is one of the sections. It matters more for this trade than almost any other.

  • Confirm how damage caused inside a customer's home during delivery is treated. Do not assume.

  • Only the sections shown as selected in your Policy Schedule apply, subject to terms and limits.

Retail Insurance for Furniture Shops: What Cover Can Include

The Lukango retail business insurance product can include property damage, public and products liability, business interruption following insured damage, money and assault and goods in transit. For a furniture retailer that means the showroom and its fit-out, the floor stock and the pieces in the stockroom, the takings, the trade lost if the showroom cannot open, and eligible stock while it is being moved. Each section is subject to eligibility, terms, exclusions, excesses and limits.

Showroom
Floor stock
Deliveries
Customers
Takings

Goods in transit

May cover eligible stock while in transit within Great Britain, including loading and unloading.

Property damage

May cover insured damage to buildings, contents and stock at the named showroom premises.

Public and products liability

Can help with certain third-party claims arising at the shop, and goods sold.

Business interruption

May cover trade lost following insured damage that stops the showroom opening.

Money and assault

Can include theft, attempted theft or robbery of business money, plus defined assault benefits.

Property extensions

May include fixed glass and signage at the showroom, within the limits in the wording.

Choosing the Right Furniture Shop Insurance Cover

Most retail trades on this product barely touch the goods in transit section. Furniture is the one that lives on it, so start there rather than treating it as an extra. After that, two questions are worth settling before you rely on anything: what happens if something is damaged inside a customer’s home while you are delivering, and whether stock you keep somewhere other than the showroom counts as stock at the named premises.

Transit is the section that earns its place

Your stock spends its last day in a van

Eligible stock can be covered while in transit within Great Britain, including loading and unloading, subject to the limits in the wording. For this trade that is not a footnote.

Delivering into a home

The thing to settle before anything else

A scuffed wall or a gouged floor on a delivery is third-party damage away from the shop. How that is treated is a question for the quote, not for a general web page.

Stock kept somewhere else

Warehouses, lock-ups, containers

Property damage responds at the premises named in your Schedule. Furniture is bulky and often stored off site, so any second location has to be declared rather than assumed.

A few items, a very large figure

Sofas and beds add up fast

A showroom holds fewer things than most shops and each is worth far more. Set the sum insured against what replacing the floor stock would actually cost today.

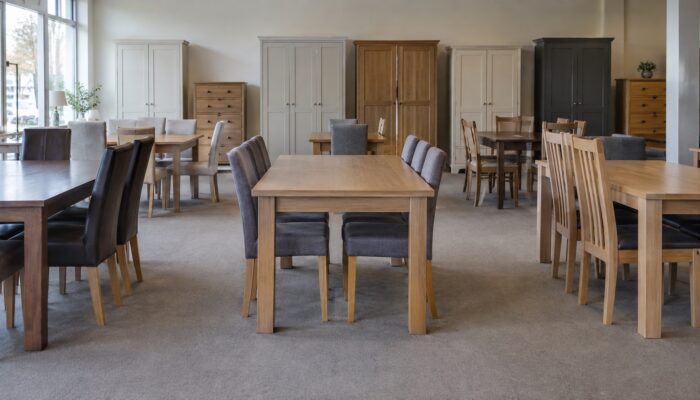
Dining tables and chairs on a furniture showroom floor with wardrobes and a chest of drawers along the wall behind

Furniture Retail Insurance: Showroom, Stock and Deliveries

Furniture shop insurance under this product is cover for the showroom and the business property in it. Property damage can include buildings, contents and stock at the premises named in your Schedule, where the section is selected and the loss is caused by an insured peril. That is the fit-out, the displays and the pieces held for sale. Goods in transit can cover eligible stock while it is being moved within Great Britain, including loading and unloading. Stock kept at a second address, and damage caused inside a customer’s home, are separate questions for the quote. The Policy Schedule confirms which sections apply.
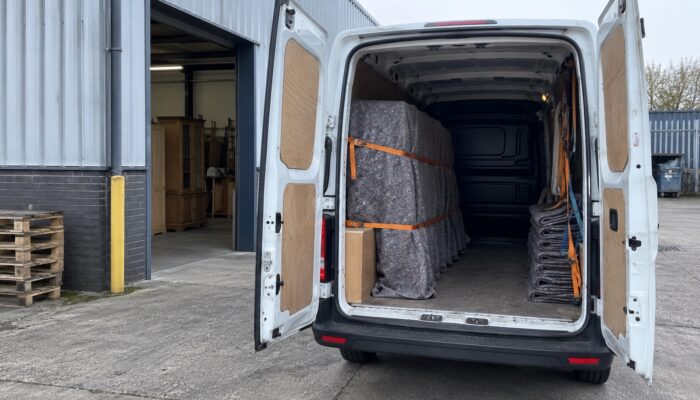
The open back of a delivery van at a furniture shop's loading door, moving blankets and straps inside and a wrapped item strapped in place

Why Find Furniture Shop Insurance Through Insureworks?

Insureworks is here to make finding insurance simple and transparent, and for a furniture retailer that means pointing at the section most shops skim. Goods in transit is part of this product, and your stock is in a van far more often than most shops’ stock is. The other side of the same round is the bit to settle early: damage inside somebody’s house while delivering happens away from the shop, and how that is treated needs confirming when you quote. This page is information only and is not personal advice. Insureworks is not the insurer and does not underwrite or pay claims.

How Furniture Shop Cover Works

  • Confirm how damage caused inside a customer's home during a delivery is treated, because it happens away from the shop.
  • Declare any stock kept away from the showroom, because property damage responds at the premises named in your Schedule.
  • Review the IPID, Policy Schedule and policy wording to understand the selected cover, its limits, excesses, conditions and exclusions.
  • Notify a claim as soon as possible, provide requested evidence and report theft, malicious damage or criminal acts to the police.

Furniture Shop Insurance FAQs

Four questions we are asked most often about insuring a furniture shop.

Goods in transit is one of the sections in this product and can cover eligible stock while it is in transit within Great Britain, including loading and unloading, where the section is selected and subject to its limits and conditions. For furniture retail this matters more than for almost any other trade on the product, so it is worth reading the limits properly rather than assuming them.

That is the question to settle before you rely on anything here. It is third-party property damage, but it happened at a customer’s address rather than at your shop, and this page cannot tell you how your policy treats work away from the premises. Get it confirmed in writing at quote stage, because it is the most likely claim this trade has.

Not automatically. The property damage section responds at the premises named in your Schedule, so a warehouse, lock-up or container at another address has to be declared and shown on the Schedule rather than assumed to be included. Furniture is bulky enough that off-site storage is normal, which is exactly why it is worth checking.

On what it would cost to replace today rather than on what you paid. A showroom holds far fewer items than most shops and each one carries a much larger figure, so a small miscount is a large shortfall. Review the sum insured at renewal and whenever your range or your buying pattern changes materially.

Latest Retail Business Insurance Content