Caterers Insurance for Catering Contractors

Caterers work away from their own kitchen, carry equipment and food to venues and serve the public when they get there. We have partnered with Lukango on a business insurance product for caterers in Great Britain. Cover is subject to the Policy Schedule, terms, conditions, exclusions and limits.
Get Your Retail Business Insurance Quote It only takes a few minutes
Quick and easy checkout
No hidden fees
Online and phone support

Catering Business Cover Explained

  • For caterers and catering contractors in Great Britain, where the trade is on the accepted list.

  • Only the sections shown as selected in your Policy Schedule apply, subject to terms, exclusions and limits.

  • Property cover attaches to your named premises, so consider separately what happens away from them.

  • Goods in transit is the section that follows equipment and food to a venue, within Great Britain.

Retail Insurance for Caterers: What Cover Can Include

The Lukango business insurance product can include property damage, public and products liability, business interruption following insured damage, money and assault, goods in transit and loss of licence. For a caterer that usually means the kitchen or unit you work from and its contents, the equipment and food you move to a venue, liability to the people you serve and to the food itself, and the trade lost if you cannot operate. Each section is subject to eligibility, terms, conditions, exclusions, excesses and limits.

Premises
Equipment
Transit
Guests
Trade

Property damage

May cover insured damage to buildings, contents and stock at your named premises.

Public and products liability

Can help with certain legal liabilities relating to guests and to the food you supply.

Business interruption

May cover trade lost following insured damage that stops you operating from the premises.

Money and assault

Can include theft, attempted theft or robbery of business money, plus defined assault benefits.

Goods in transit

May cover eligible goods while in transit within Great Britain, including loading and unloading.

Loss of licence

Can cover financial loss following suspension, withdrawal or refusal to renew an alcohol licence.

Choosing the Right Caterers Insurance Cover

Before buying caterers insurance, customers should compare the cover available with how they actually work: where the kitchen is, how much of the job happens off site, the value of equipment carried, how far it travels, annual turnover, how payment is taken and whether alcohol is served. It is also important to read the IPID, the Policy Schedule and the full policy wording, paying close attention to exclusions, excesses, limits, sub-limits and conditions. This page is information only.

Working away from base

Premises cover has an address

Property damage attaches to the premises named in your Schedule. Work done at a client's venue is a different question, and it is the one most worth asking before you buy.

Kit in the van

Goods in transit, within Great Britain

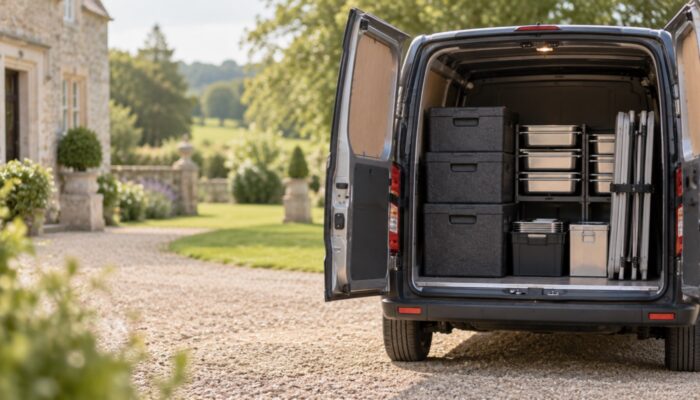
Goods in transit can cover eligible goods on the move, including loading and unloading. Consider what you carry on a normal job and what it would cost to replace at short notice.

The food you serve

Products liability, not just public liability

Products liability relates to the goods you supply, which for a caterer means every plate that goes out. It is worth understanding properly before comparing one premium with another.

Serving alcohol at events

Suspension, withdrawal or refusal

Loss of licence covers financial loss where a licence is suspended, withdrawn or not renewed. Worth weighing if a share of your income depends on serving drinks.

Open rear doors of a catering van loaded with insulated boxes, trays and a folded trestle table

Catering Insurance: Premises, Transit and Liability

Catering insurance can bring several practical risks into one policy framework, but it helps to see where each one sits. For this product, property damage can include buildings, contents and stock at the premises named in your Schedule, where the section is selected and the loss is caused by an insured peril. Goods in transit is the section that deals with eligible goods on the move within Great Britain. Public and products liability relates both to the people you serve and to the food you supply them. The Policy Schedule confirms which sections apply, the sums insured, excesses, sub-limits and any endorsements.
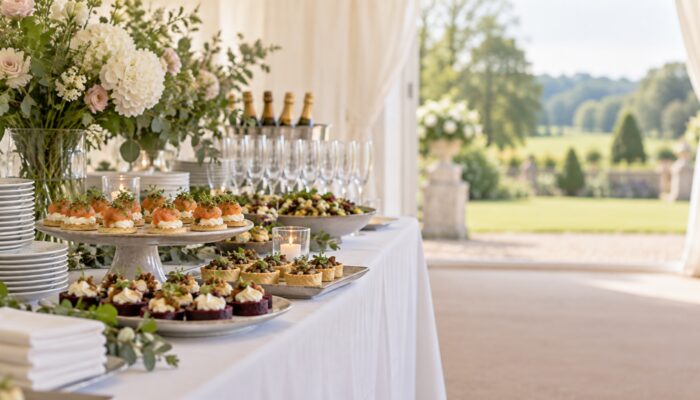
A long buffet table set with platters, plates and glassware at an event

Why Find Event Catering Insurance Through Insureworks?

Insureworks is here to make finding insurance simple and transparent. For catering contractors that means partnering with insurers who set out covered areas, common restrictions and policy documents in plain English, without implying every caterer needs the same cover. This page is information only and is not personal advice. Insureworks is not the insurer and does not underwrite or pay claims. Food safety and hygiene obligations sit with you as the operator and are not insurance matters. Read the IPID, Schedule and wording before buying.

How Catering Business Cover Works

  • Work out which parts of the job happen at your own premises and which happen elsewhere, because the sections differ.
  • Review the IPID, Policy Schedule and policy wording to understand the selected cover, its limits, excesses, eligibility conditions and exclusions.
  • Provide complete and accurate information when arranging, renewing or changing the policy, including your activities, premises and any material changes.
  • Notify a claim as soon as possible, provide requested evidence and report theft, malicious damage or criminal acts to the police.

Caterers Insurance FAQs

Four questions we are asked most often about insuring a catering business.

Property damage under this product attaches to the premises named in your Policy Schedule, so it is not a general cover for work at someone else’s site. Goods in transit can cover eligible goods on the move, and public and products liability can respond to third party injury or damage subject to its terms. Check the wording carefully for how off site work is treated before you buy.

Goods in transit can cover eligible goods while in transit within Great Britain, including loading and unloading, where that section is shown as selected in your Policy Schedule. Limits, excesses and security conditions apply. Consider what you routinely carry, and what it would cost to replace at short notice during a busy season.

Products liability can help with certain legal liabilities relating to the goods you supply, which for a caterer means the food and drink served to guests. It applies where the section is selected and the policy conditions are met, and limits apply. It does not replace your own food safety and hygiene obligations, which remain yours as the operator.

Business interruption can cover trade lost following insured damage that stops you operating from the premises, where the section is selected. Separately, if the premises are left unoccupied for more than thirty consecutive days, cover is restricted and only limited cover applies. Both are worth checking against your Policy Schedule.

Latest Retail Business Insurance Content