Cafe Insurance for Coffee Shops and Sandwich Bars

Cafes serve food and drink to the public all day, run equipment that has to keep working and hold stock that spoils. We have partnered with Lukango on a business insurance product for cafes in Great Britain. Cover is subject to the Policy Schedule, terms, conditions, exclusions and limits.
Get Your Retail Business Insurance Quote It only takes a few minutes
Quick and easy checkout
No hidden fees
Online and phone support

Cafe Business Cover Explained

  • For cafes, coffee shops and sandwich bars in Great Britain, where the trade is on the accepted list.

  • Only the sections shown as selected in your Policy Schedule apply, subject to terms, exclusions and limits.

  • Products liability matters more here than in most retail, because you are serving food and drink.

  • Equipment and stock sit close together in a cafe, so consider both when you set your sums insured.

Retail Insurance for Cafes: What Cover Can Include

The Lukango business insurance product can include property damage, public and products liability, business interruption following insured damage, money and assault, goods in transit and loss of licence. For a cafe that usually means the premises and their contents, the coffee machine and catering equipment, the stock behind the counter, liability to customers seated in and passing through, and the trade lost if you cannot open. Each section is subject to eligibility, terms, conditions, exclusions, excesses, limits and sub-limits.

Premises
Equipment
Stock
Customers
Trade

Property damage

May cover insured damage to buildings, contents and stock at the named cafe premises.

Public and products liability

Can help with certain legal liabilities relating to customers and to the food you serve.

Business interruption

May cover trade lost following insured damage that stops the cafe opening.

Money and assault

Can include theft, attempted theft or robbery of business money, plus defined assault benefits.

Goods in transit

May cover eligible goods while in transit within Great Britain, including loading and unloading.

Loss of licence

Can cover financial loss following suspension, withdrawal or refusal to renew an alcohol licence.

Choosing the Right Cafe Insurance Cover

Before buying cafe insurance, customers should compare the cover available with their own trading: the size of the premises, seating inside and out, the value of catering equipment, how much stock is held, annual turnover, how cash is handled and whether alcohol is served. It is also important to read the IPID, the Policy Schedule and the full policy wording, paying close attention to exclusions, excesses, limits, sub-limits and conditions. This page is information only and does not recommend a policy.

The food you serve

Products liability, not just public liability

Products liability relates to the goods you supply, which in a cafe means everything that leaves the counter. It is worth understanding before you compare one premium against another.

Equipment that has to work

Machines, fridges and counters

Catering equipment is expensive to replace and easy to under-insure. Consider what it would cost to replace the coffee machine, the chillers and the counters together, not one at a time.

Stock behind the counter

Fresh, chilled and fast moving

Cafe stock turns over quickly and much of it is perishable. A sum insured set in a quiet month may not reflect what is actually on the premises at your busiest.

Customers in and out

Hot drinks, tiled floors, tight spaces

Public liability relates to injury or damage to third parties on your premises. Consider your footfall at peak times, and the limits shown in your Policy Schedule.

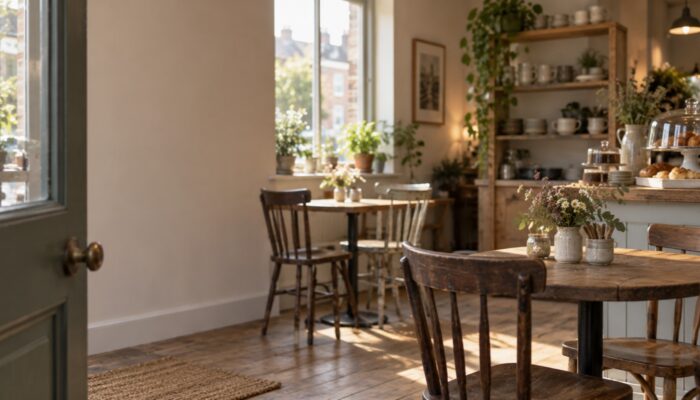
Tables and wooden chairs in a small sunlit cafe with a shelf of cups and a plant

Coffee Shop Insurance: Premises, Equipment and Liability

Coffee shop insurance can bring several practical risks into one policy framework. For this product, property damage can include buildings, contents and stock where the section is selected and the loss is caused by an insured peril. Public and products liability relates both to customers on the premises and to the food and drink you supply them, which is the part that sets food retail apart. The Policy Schedule confirms which sections apply, the sums insured, excesses, sub-limits and any endorsements, and should be checked before purchase and after any change to the business.
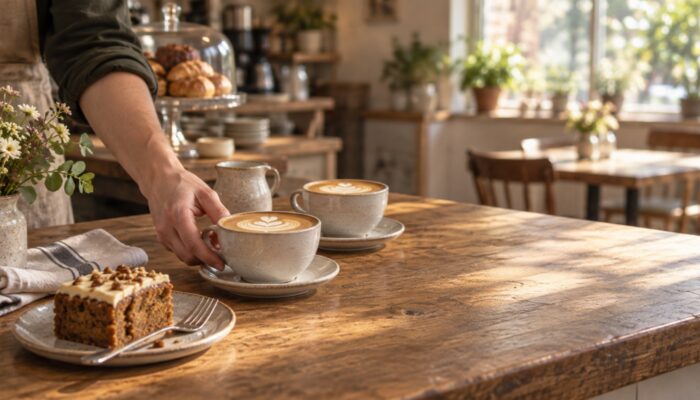
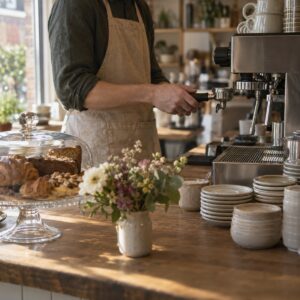
Two coffees and a slice of cake on a timber counter, a hand sliding one cup forward

Why Find Sandwich Shop Insurance Through Insureworks?

Insureworks is here to make finding insurance simple and transparent. For sandwich shops and cafes that means partnering with insurers who set out covered areas, common restrictions and policy documents in plain English, without implying every cafe needs the same cover. This page is information only and is not personal advice. Insureworks is not the insurer and does not underwrite or pay claims. Food safety and hygiene obligations sit with you as the operator and are not insurance matters. Read the IPID, Schedule and wording before buying.

How Cafe Business Cover Works

  • Choose the cover sections that appear relevant to the cafe, such as property damage, liability, business interruption or money and assault.
  • Review the IPID, Policy Schedule and policy wording to understand the selected cover, its limits, excesses, eligibility conditions and exclusions.
  • Provide complete and accurate information when arranging, renewing or changing the policy, including your activities, the premises and any material changes.
  • Notify a claim as soon as possible, provide requested evidence and report theft, malicious damage or criminal acts to the police.

Cafe Insurance FAQs

Four questions we are asked most often about insuring a cafe.

Products liability can help with certain legal liabilities relating to the goods you supply, which for a cafe means the food and drink sold to customers. It applies where the section is shown as selected in your Policy Schedule and the policy conditions are met, and limits apply. It is not a substitute for your own food safety and hygiene obligations, which remain yours.

Catering equipment can be included as contents under the property damage section, where that section is selected. Cover responds to insured perils rather than to every cause of loss, and to breakdown only if the wording provides for it. The sum insured should reflect what it would cost to replace the equipment you actually have on site.

Stock held for sale can be included under property damage where the section is selected and the loss is caused by an insured peril. Perishable stock in a cafe raises particular questions, so check the wording for what is and is not included, along with the limits and excesses shown in your Policy Schedule, before you buy.

If the premises are left unoccupied for more than thirty consecutive days, cover is restricted and only limited cover applies, as set out in the policy wording. That matters for refurbishment or a seasonal closure. It is one of the first conditions to check against your Policy Schedule if the cafe will stand empty.

Latest Retail Business Insurance Content