Butchers Insurance for the Shop Itself

This is cover for a butcher's retail shop: the premises, the counters and display chillers, the equipment, the takings and liability for the meat you sell. How chilled and frozen stock is treated if refrigeration fails is the first thing to confirm, because that is where this trade's biggest loss usually comes from.
Get Your Retail Business Insurance Quote It only takes a few minutes
Quick and easy checkout
No hidden fees
Online and phone support

Butcher Shop Cover Explained

  • For butchers' retail shops in Great Britain, where the trade is on the accepted list.

  • The accepted trade is retail. Wholesale supply, cutting plants and abattoirs need checking first.

  • Confirm how chilled and frozen stock is treated if refrigeration fails. Do not assume it is included.

  • Only the sections shown as selected in your Policy Schedule apply, subject to terms and limits.

Retail Insurance for Butchers: What Cover Can Include

The Lukango retail business insurance product can include property damage, public and products liability, business interruption following insured damage, money and assault and goods in transit. For a butcher that means the shop and its fit-out, the counters, display chillers and equipment, the takings, the trade lost if the shop cannot open, and liability for the meat and products you sell. Each section is subject to eligibility, terms, exclusions, excesses and limits.

Premises
Chillers
Equipment
Customers
Money

Products liability

Can help with certain claims arising from the meat and food you have sold.

Property damage

May cover insured damage to buildings, contents and stock at the named shop premises.

Public liability

Can respond to certain third-party injury or damage claims arising at the shop.

Business interruption

May cover trade lost following insured damage that stops the shop opening.

Money and assault

Can include theft, attempted theft or robbery of business money, plus defined assault benefits.

Goods in transit

May cover eligible stock while in transit within Great Britain, including loading and unloading.

Choosing the Right Butchers Insurance Cover

The first question with butchers insurance is what happens when the chiller stops. Property damage responds to insured perils such as fire, flood and theft, and a refrigeration failure that spoils a counter full of meat is a different kind of loss, commonly handled as its own extension. Settle that before anything else. After that, products liability is the section this trade should read first, because you sell food that people eat.

When the chiller stops

The first thing to settle, before anything else

Spoiled stock after a refrigeration failure is the loss most likely to hit a butcher, and it is commonly handled separately from fire and flood. Confirm how it is treated before you quote.

Products liability is included

And for a butcher it is the important one

You sell food that people eat, so the section covering claims arising from what you have sold matters more here than almost anywhere. It is one of the six sections in this product.

Retail, not wholesale

Abattoirs and cutting plants are different trades

The occupancy on the accepted list is a butcher's retail shop. If you supply trade customers at volume or process off site, check eligibility rather than assuming this fits.

Food hygiene is not insurance

And no policy changes that

Your food safety obligations, records and inspections sit outside any insurance policy. Nothing on this page reduces them, and good practice is what keeps most claims from happening.

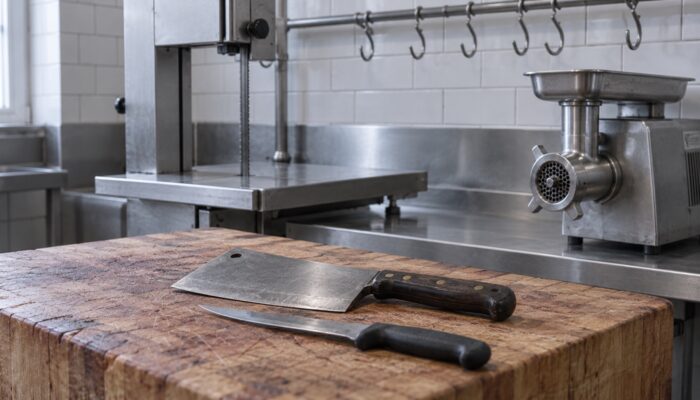
A butcher's wooden block with a cleaver and boning knife, a bandsaw and mincer on the steel bench behind

Butcher Shop Insurance: Premises, Chillers and Equipment

Butchers insurance under this product is cover for the shop and the business property in it. Property damage can include buildings, contents and stock at the premises named in your Schedule, where the section is selected and the loss is caused by an insured peril. That is the fit-out, the counters and display chillers, the block, the saws and the mincers. Products liability can respond to certain claims arising from the meat you have sold. How spoiled stock after a refrigeration failure is treated is a separate question for the quote. The Policy Schedule confirms which sections apply and their limits.
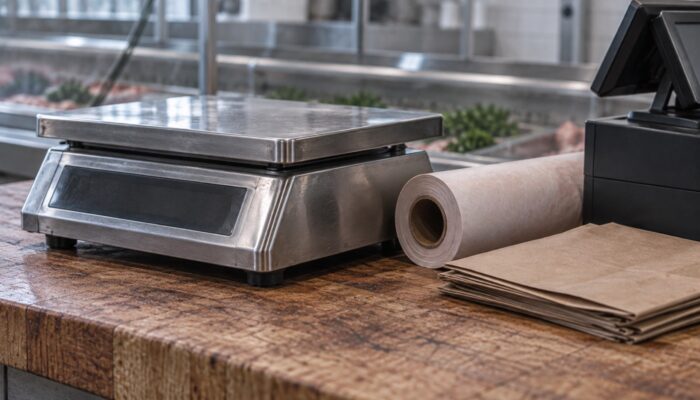
A stainless steel scale, a roll of butcher's paper and paper bags on a butcher's timber counter

Why Find Butcher Shop Insurance Through Insureworks?

Insureworks is here to make finding insurance simple and transparent, and for a butcher that means putting the cold chain question first instead of last. The loss that most often hurts this trade is a chiller failing overnight, and that is commonly handled separately from fire and flood, so it needs confirming when you quote. What this product does carry, and it matters here more than in most shops, is products liability for the food you sell. This page is information only and is not personal advice. Insureworks is not the insurer and does not underwrite or pay claims.

How Butcher Shop Cover Works

  • Confirm first how chilled and frozen stock is treated if refrigeration fails, because that is this trade's likeliest loss.
  • Review the IPID, Policy Schedule and policy wording to understand the selected cover, its limits, excesses, conditions and exclusions.
  • Provide complete and accurate information when arranging, renewing or changing the policy, including your activities and any material changes.
  • Notify a claim as soon as possible, provide requested evidence and report theft, malicious damage or criminal acts to the police.

Butchers Insurance FAQs

Four questions we are asked most often about insuring a butcher’s shop.

That is the question to settle before anything else, and this page cannot answer it for your shop. Property damage responds to insured perils such as fire, flood and theft, and spoiled stock following a refrigeration breakdown is commonly handled as a separate extension rather than part of the main section. Get it confirmed in writing at quote stage.

Products liability can respond to certain third-party claims arising from the food you have sold, where that section is shown as selected in your Policy Schedule and subject to its terms, limits and exclusions. For a butcher it is usually the section worth reading first. It does not replace your food safety obligations, which sit outside any policy.

It is worth raising at quote stage. The occupancy on the accepted list is a butcher’s retail shop, so a business with a meaningful wholesale or trade supply side does not automatically fit it. Abattoirs and off-site cutting plants sit outside it as well. Settle it before you rely on anything here rather than at the point of a claim.

Equipment of that kind can be included as business contents at the premises named in your Schedule where the property damage section is selected. Cover responds to insured perils rather than every cause of loss, so mechanical breakdown is worth asking about separately, in the same conversation as the refrigeration question.

Latest Retail Business Insurance Content