Product: Business

Takeaway Liability Insurance

Takeaway insurance through this product is about liability: customers at the counter, the food you serve and the staff in your kitchen. We have partnered with Lukango on a liability insurance product for takeaways in Great Britain, subject to the Policy Schedule, terms, conditions, exclusions and limits.
Get Your Retail Business Insurance Quote It only takes a few minutes
Quick and easy checkout
No hidden fees
Online and phone support

Takeaway Business Insurance Explained

  • For takeaways in Great Britain, where takeaway is the trade shown on the accepted list, from fast food counters to delivery kitchens.

  • This product provides public and products liability and employers’ liability only, with no buildings, contents, stock or business interruption cover.

  • Products liability can relate to injury caused by food you sell. Product recall is excluded, and delivery vehicles need motor insurance.

  • Public liability relates to injury or damage to other people, such as a customer slipping at the counter.

Takeaway Shop Insurance: What Cover Can Include

For takeaways, the Lukango business insurance product provides two sections: public and products liability, and employers’ liability. Public liability can help with certain legal liabilities for injury to customers or visitors, or damage to their property, arising from your business. Products liability can relate to injury caused by food or drink you sell. It does not cover your premises, fryers, stock or takings. Cover is subject to the Policy Schedule, terms, exclusions and limits.

Injury
Products
Staff
Legal
Damage

Public liability

Can help with certain legal liabilities for injury to customers and visitors at your takeaway.

Food and drink

Can relate to injury caused by food or drink you sell, subject to the wording’s terms.

Employers’ liability

Can cover legal liability for injury to kitchen and counter staff you employ, with nil excess.

Defence costs

Can include legal costs of defending a covered claim, within the limits set out in the wording.

Health and safety

Can include legal expenses for defending certain health and safety prosecutions, within the wording limits.

Third-party property

Can respond to accidental damage to other people’s property, such as a neighbouring shop.

Choosing the Right Takeaway Insurance

Before buying takeaway insurance, check what you actually need to insure: whether you own or lease the premises, the value of your fryers, fridges and fit-out, your food stock, how many staff you employ, and whether you deliver or offer collection. Read the policy wording and Policy Schedule carefully, including the exclusions and limits. This page explains the cover in general terms and is not a recommendation.

Your kitchen

Premises and equipment

There is no buildings, contents or equipment cover for takeaways, so fryers, fridges, the fit-out and the premises need insuring separately if you are responsible for them.

Food stock

Spoiled stock and recall

There is no stock cover, so food lost to a fridge failure or power cut is not covered, and product recall is excluded under products liability.

Deliveries

Vans, cars and scooters

Vehicles that need compulsory motor insurance are excluded from public liability, so delivery vehicles need their own motor policy that covers business use, including food delivery.

Your team

Kitchen and counter staff

If you employ people, employers’ liability is usually a legal requirement. It is one of the two sections here, subject to the limit in your Schedule.

Takeaway kitchen with fryers, extraction hood and a fridge

Takeaway Insurance Covers Liability, Not the Premises

Takeaway insurance through this product is built around liability rather than property. Public liability relates to the people around you: a customer who slips on a wet floor by the counter, or a passer-by hurt by something outside your shop. Products liability can relate to injury caused by food or drink you sell, subject to the terms of the wording. Employers’ liability relates to injury to your own staff. What it does not include is cover for the premises, fryers, food stock, takings, delivery vehicles or business interruption, so those need to be arranged separately.
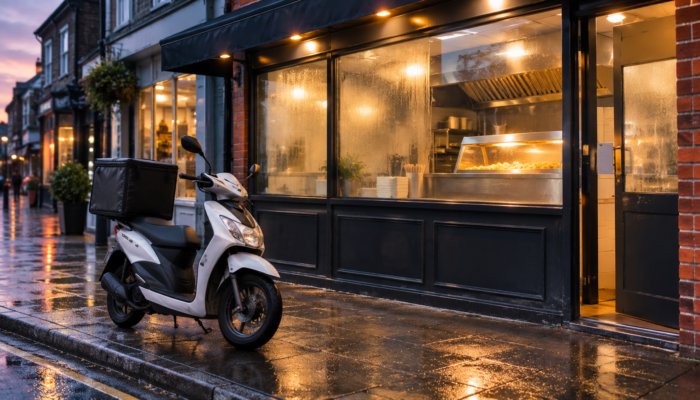
Delivery scooter with an insulated box outside a takeaway at dusk

Why Find Takeaway Business Insurance Through Insureworks?

Insureworks is here to make finding insurance simple and transparent. For takeaways that means partnering with insurers who explain what may be covered and what is not in plain English, starting with the fact that this is liability cover only, whether you need takeaway shop insurance or fast food takeaway insurance for a delivery kitchen. This page is information only and is not personal advice. Insureworks is not the insurer and does not underwrite or pay claims. Read the policy wording and Schedule before buying, so you understand exactly what is and is not included.

How Takeaway Insurance Works

  • Check that liability cover fits your takeaway, and decide how the premises, kitchen equipment and food stock will be insured, since they are not included.
  • Review the policy wording and Policy Schedule to understand the selected cover, its limits, excesses, eligibility conditions and exclusions before buying.
  • Give complete and accurate information about your takeaway, including cooking methods, deliveries, staff numbers, turnover and any changes during the year.
  • Notify a claim as soon as possible, provide the evidence requested and do not admit liability or agree a settlement yourself.

Takeaway Insurance FAQs

Four questions we are asked most often about insuring a takeaway.

No. For takeaways this product provides public and products liability and employers’ liability only. There is no buildings, contents, equipment, stock, money or business interruption cover, so fryers, fridges, the fit-out and food stock need insuring separately if you are responsible for them. Check the policy wording and Schedule for exactly what is included.

Products liability can relate to injury caused by food or drink you supply, subject to the terms, exclusions and limits of the policy wording. Product recall is excluded. Public liability is separate and relates to accidents such as a customer slipping at the counter. Check the wording for the conditions that apply to the food you prepare.

Not on the road. Public liability excludes vehicles that need compulsory motor insurance, so incidents involving a car, van or scooter used for deliveries fall under the motor policy. Make sure that policy covers business use, including food delivery. Employers’ liability relates to injury to employees in the course of their work.

Most businesses that employ people are legally required to hold employers’ liability insurance. It is one of the two sections in this product and relates to injury to your employees in the course of their work, including kitchen and counter staff. Check the section is shown as selected in your Policy Schedule and that the limit suits your team.

Latest Retail Business Insurance Content